Finding the right UK online banks for non residents is an important step for overseas entrepreneurs who own or plan to establish a UK limited company. Although traditional banks can be difficult to access without UK residency, some digital banking and financial technology providers offer business accounts with remote application processes, subject to their eligibility requirements.
For international founders, choosing a UK business bank account for non residents involves more than comparing monthly fees. You also need to consider where you live, how your company operates, whether you receive international payments, which currencies you use and how your funds are protected.
For international founders, choosing a UK business bank account for non residents involves more than comparing monthly fees. You also need to consider where you live, how your company operates, whether you receive international payments, which currencies you use and how your funds are protected.
At Form My Company, we help international entrepreneurs establish UK companies and connect with banking options suitable for their business circumstances. This guide compares the main providers, explains the differences between online and traditional banking, and outlines the documents and checks typically required before applying.
Quick answer: Wise Business and Airwallex are worth comparing for international payments and multi-currency operations. Revolut Business offers digital business tools for eligible applicants, while Tide and Starling may be relevant for UK-focused banking needs subject to their individual eligibility rules. No provider is suitable for every non-resident, so confirm your eligibility before applying.
Best UK Business Bank Accounts for Non-Residents
The best UK business bank account for non residents depends on your country of residence, company structure, transaction requirements and preferred banking features. The following comparison highlights providers to investigate rather than guaranteeing that every overseas applicant will qualify.
| Provider | Best suited to | International features | Important consideration |
|---|---|---|---|
| Wise Business | Businesses receiving and sending international payments | Multi-currency balances and international transfers | An e-money service rather than a conventional bank account |
| Revolut Business | Eligible companies wanting digital financial management | Multi-currency services, transfers and business tools | Applicant residence and company eligibility requirements apply |
| Airwallex | Businesses managing global payments | Multi-currency accounts and international payment services | Availability depends on business and applicant eligibility |
| Tide | Businesses seeking UK-focused digital business account services | UK business payment and account management features | Check current eligibility and the banking provider behind the account |
| Starling Bank | Eligible businesses seeking a UK digital bank | UK business banking and app-based account management | Its published eligibility criteria require relevant directors and controllers to meet UK residency requirements |
Provider features and eligibility are based on published information and should be confirmed directly before applying. Wise’s current pricing and service structure are available on its official website, while Revolut publishes its Business eligibility requirements. Starling also publishes business account eligibility criteria.
Wise Business: International Payments and Multiple Currencies
Wise Business is an option for companies that receive payments from overseas customers, pay international suppliers or need to manage funds in different currencies.
Its services include international transfers and multi-currency functionality, subject to the currencies and services available to the applicant. This can be useful for a UK company whose owner lives abroad and whose customers or suppliers operate in several countries.
Wise is an electronic money institution rather than a conventional bank. Its safeguarding arrangements are different from FSCS deposit protection, so business owners should understand how their funds are held before using the service.
Review the current fees, supported countries and available account features on the Wise Business pricing page.
Revolut Business: Digital Banking Tools for Eligible Companies
Revolut Business offers digital financial services for companies that meet its application criteria. Its features can be relevant to businesses seeking multi-currency functionality, payment management and business spending tools.
However, an overseas director should not assume that a UK company automatically qualifies. Revolut considers the company’s registration and the applicant’s country of residence, among other requirements.
Review the official Revolut Business eligibility guidance before beginning an application.
Airwallex: Global Business Accounts
Airwallex is designed for businesses with international payment and financial management requirements. Its services can be relevant to companies working with overseas suppliers, international customers and distributed teams.
Businesses considering an international business account should compare supported currencies, transfer charges, account functionality and the countries accepted for onboarding.
Airwallex is not a conventional bank. Its UK services include electronic money arrangements, and its funds protection structure should be reviewed separately from FSCS-protected bank deposits. Read its UK business account guidance.
Tide: UK-Focused Business Account Services
Tide is worth investigating for companies that want app-based business account services and tools for managing everyday UK transactions.
Before applying, overseas directors should verify the provider’s current eligibility conditions and establish which financial institution provides the account. The availability of an account, its features and any deposit protection depend on the specific product and applicable terms.
Tide should not be treated as a guaranteed option for every non-UK resident.
Starling Bank: A UK Digital Banking Option
Starling Bank offers business banking through a digital platform and may suit companies that meet its eligibility criteria.
However, Starling’s published requirements state that directors accessing a business account must be UK residents. This makes it less suitable for many businesses whose directors live entirely overseas.
Check the bank’s official business account eligibility requirements before including it in your shortlist.
Businesses selling through online stores and marketplaces may have additional payment and currency requirements. Our guide to business bank accounts for non-resident e-commerce founders explores these specific needs.
Online and Digital Banks vs High-Street Banks
When comparing a UK bank for non residents, it is important to distinguish between the way an account is accessed and the type of institution providing it.
Online banking describes how you manage an account. It does not necessarily mean that the provider holds a banking licence or that its services are available in every country.
Online Business Accounts
Digital providers allow eligible businesses to complete much of the application process online. Depending on the provider, account management may include transfers, payment details, debit cards, multi-currency services and financial reporting tools.
These features can help overseas founders manage a UK company without regularly visiting the country.
Nevertheless, remote applications still involve identity verification, business checks and eligibility assessments. An online application does not guarantee approval.
Traditional High-Street Banks
Established UK banks may provide a broader range of banking services, but their business account requirements can be restrictive for overseas owners.
Some require directors or people with account access to reside in the UK, and their onboarding procedures may involve additional documentation or in-person verification.
Companies with existing international banking relationships may have other options, but these depend on the bank, the business structure and the countries involved.
Which Option Is Better for an Overseas Director?
A digital provider may be more convenient when remote access, international transfers and multi-currency features are priorities. A conventional bank may be more appropriate where the business qualifies for its account and requires services specific to that institution.
Compare the actual eligibility rules and account terms rather than assuming that every digital provider accepts non-residents or that every traditional bank rejects them.
International Business Accounts: Multi-Currency and Global Payments
An international business bank account can help a company manage transactions across borders. However, the phrase can describe different products, including conventional bank accounts, foreign-currency accounts and electronic money services.
For a UK limited company managed from abroad, the important question is whether the provider offers the functions the business actually needs.
Multi-Currency Account Features
A multi-currency account may allow a business to hold, convert, send or receive money in supported currencies. The available functions vary by provider and account type.
Consider these requirements before choosing an account:
- Receiving customer payments in GBP, EUR, USD or other supported currencies.
- Paying suppliers and contractors in different countries.
- Converting currencies at transparent rates.
- Accessing local account details where available.
- Managing international transfers and associated charges.
- Integrating transaction records with accounting software.
A company receiving regular international payments should compare foreign exchange costs and transfer fees, not just the advertised monthly account fee.
Businesses can also compare UK business accounts for international payments to understand the available options.
International Business Banking for Overseas Companies
International business banking is particularly relevant to companies that trade in multiple markets. A suitable provider can help consolidate payments and improve visibility over business transactions.
Some companies use one account for UK operating expenses and another service for international payments. This approach may offer useful flexibility, but it also creates additional administration and potentially additional costs.
Before opening multiple accounts, check whether the arrangement fits your transaction volumes, accounting processes and cash management needs.
What Does an International Business Account Cost?
The cost of a business account for non-UK residents depends on the provider, account plan and way the business uses the service.
Rather than comparing headline prices alone, assess the complete cost of operating the account.
| Cost category | What to check |
|---|---|
| Account opening | Whether there is a setup fee or initial deposit requirement |
| Monthly subscription | Whether the account has a recurring charge |
| Domestic transfers | Charges for sending and receiving local payments |
| International transfers | Fixed fees and any intermediary bank charges |
| Currency conversion | Exchange rate markup and conversion fees |
| Payment collection | Fees for receiving transfers or using payment services |
| Cards and additional users | Charges for extra cards, employees or permissions |
| Additional services | Fees for accounting tools, support or other optional features |
Understanding Provider Pricing
Wise Business, for example, publishes a UK pricing structure that includes a one-off fee for accessing certain international account details. Its current published pricing lists a £50 one-off fee for those details, while other charges depend on the service and transaction.
Check the latest Wise Business fees before applying, as pricing and features can change.
For Revolut Business, Airwallex, Tide and other providers, consult the relevant pricing pages and account terms. Do not assume that an advertised free or low-cost account includes every payment, currency or business feature.
What Is Included With Form My Company?
Form My Company supports international entrepreneurs with UK company formation and introductions to banking partners suitable for non-resident founders.
The relevant company formation package may include company registration support and a registered office address, according to the package selected. These services are separate from the bank or financial provider’s own account fees and application requirements.
Before purchasing a package, confirm exactly what is included, what additional charges apply and whether any banking introduction is part of the selected service. An introduction does not guarantee that a provider will approve the application.
Eligibility for a UK Business Account for Non-Residents
Eligibility is one of the most important factors when selecting a UK business account for non residents. Providers assess more than the company’s country of registration.
Their decisions may depend on the applicant’s country of residence, the company’s legal structure, its business activities, its ownership and the documents available for verification.
Can an Overseas Director Open a UK Business Account?
An overseas director may be able to apply for an account for a UK company, but acceptance depends on the provider’s rules.
Some providers support eligible businesses with overseas owners, while others require relevant directors, controllers or applicants to reside in the UK or another supported country.
Before applying, check:
- Whether the provider accepts your country of residence.
- Whether your company structure is supported.
- Whether the applicant must be a director or significant owner.
- Whether personal and business addresses meet the requirements.
- Whether your industry and expected transactions are supported.
- Whether the account offers the currencies and payment functions you need.
Can Turkish Residents Open a UK Business Account?
Turkish residents should check each provider’s current country eligibility rules before applying. A UK company registration does not automatically make its overseas director eligible for every business account.
The provider may assess the applicant’s residential address, identity documents, company ownership, business activity and other information. Some services accept applicants from a defined list of countries, while others impose additional restrictions.
If you live in Turkey and own a UK limited company, confirm that the provider accepts applicants residing in Turkey and supports the proposed company structure. Do not rely solely on a general claim that an account is available to non-residents.
Know Your Customer and Anti-Money-Laundering Checks
Know Your Customer, commonly known as KYC, refers to the identity and verification checks carried out by financial providers. Anti-money-laundering checks help providers understand the business, its ownership and the purpose of its transactions.
An overseas director may be asked to provide additional information about the source of funds, expected payment volumes, customers, suppliers or business operations.
Preparing accurate documentation before applying can help reduce avoidable delays, although the provider may request further evidence.
Documents Required to Open an International Business Bank Account
The exact requirements vary between providers, but an application for a UK company account commonly involves personal identification, company records and evidence of business activity.
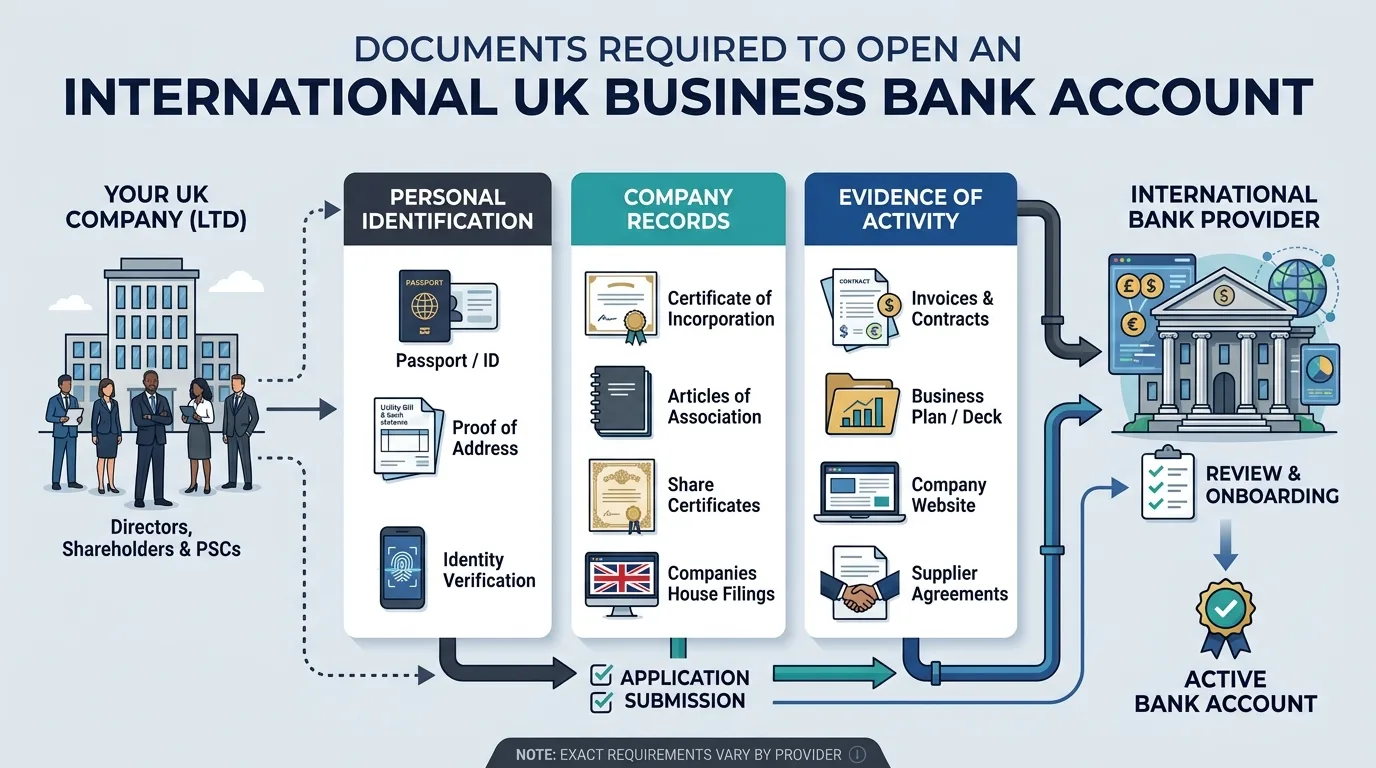
- Prepare the following where applicable:
- Identity documents: A valid passport or another accepted form of identification for directors and relevant beneficial owners.
- Proof of address: An accepted residential document, such as a bank statement or utility bill. Confirm whether international proof of address is permitted.
- Company registration details: The company’s registered name, Companies House number and Certificate of Incorporation.
- Ownership information: Details of directors, shareholders and people with significant control.
- Business address: Registered office details and, where required, evidence of the operating address.
- Business activity evidence: A company website, invoices, supplier contracts or other documents explaining what the business does.
- Expected transaction information: Anticipated turnover, payment volumes, currencies and countries involved in trading.
Providers may request additional documents depending on the application and risk assessment. A registered office address does not automatically satisfy a requirement for proof of personal residence or operational presence.
How to Prepare Before Applying
First, confirm that the business is registered and its details are accurate. Then check the provider’s country restrictions and collect the required identity and company documents.
Make sure the information submitted about the business, its address, ownership and expected activity is consistent. If the provider asks for further evidence, respond through its official application process.
Applying to a provider that supports your circumstances is more useful than submitting multiple applications without checking the eligibility criteria.
How to Choose the Best Bank Account for International Business
The best bank account for international business depends on the company’s operating model rather than a single universal ranking.
Choose Based on Your Payment Requirements
If your company mainly receives and sends international payments, prioritise supported currencies, exchange rates, local account details and international transfer costs.
If you mainly make payments within the UK, examine domestic transfer facilities, card services, accounting integrations and routine account charges.
If the company holds significant working capital, investigate how the provider holds customer funds and whether eligible deposits receive FSCS protection.
New companies may need to balance account fees, payment features and future growth. Read our guide to business bank accounts for non-resident startups for a startup-focused comparison.
Consider Accounting and Administration
An account that connects with your accounting software may reduce manual reconciliation and simplify financial reporting.
Review available integrations, downloadable statements, payment references, user permissions and transaction reporting before choosing a provider.
Compare the Complete Service
A useful comparison should include eligibility, fees, transaction capabilities, customer support, account protection and ease of administration.
Do not choose a provider based solely on a promotional offer or an advertised opening time. The account must remain suitable for the company’s ongoing operations.
Bank Accounts and Financial Protection: What Non-Residents Should Know
Not every international business account is provided by a licensed bank. Some financial technology providers operate as electronic money institutions and safeguard customer funds under the applicable regulatory framework.
Safeguarding and FSCS deposit protection are not interchangeable.
Eligible deposits held with authorised banks may qualify for FSCS protection, subject to the scheme’s rules and limits. Funds held with an electronic money institution are generally safeguarded under a different arrangement and do not receive FSCS deposit protection simply because the provider is FCA-authorised.
Before opening an account, establish which institution provides the service, how customer funds are held and what protection applies to the specific product. Consult the provider’s current legal disclosures and the relevant official protection guidance.
How Form My Company Helps Overseas Entrepreneurs
Form My Company supports overseas entrepreneurs who want to establish a UK limited company and explore suitable banking options.
Our support focuses on the company formation process and introductions to banking providers that may be appropriate for non-resident owners.
Depending on the selected service package, company formation support can help you obtain the registration details and documents needed when preparing a banking application. You should still review each provider’s requirements independently and ensure your application contains accurate information.
Bank account approval remains the decision of the financial provider. Eligibility, processing times and available services depend on its checks and terms.
Company Formation and Banking Support: What to Expect
The process starts with establishing your company and confirming the services included in your chosen package. You can then identify potential account providers based on your residence, company structure and financial requirements.
Before proceeding, confirm the package price, included services, any additional charges and the scope of any banking introduction.
For further information, visit Form My Company to explore company formation support for international entrepreneurs.
Frequently Asked Questions
Which UK online banks accept non-residents?
Some digital and financial technology providers support eligible UK companies with overseas owners. Wise Business, Revolut Business and Airwallex are options to investigate, while Tide and Starling have their own eligibility requirements. Availability depends on the applicant’s residence, company structure and the provider’s current terms.
What is the best UK business bank account for non-residents?
There is no single best account for every non-resident. Wise Business and Airwallex are worth comparing for international payments, while Revolut Business offers digital business services to eligible applicants. Compare fees, currencies, eligibility and funds protection before deciding.
Can I open an international business bank account online?
Some providers allow eligible applicants to complete most or all of their application online. You will still need to supply the requested identity, address and company documents and complete any additional verification. Online applications do not guarantee approval.
Can Turkish residents open a UK company bank account?
Turkish residents must check the country eligibility rules of each provider. Some providers restrict applications based on the applicant’s country of residence, even when the company is registered in the UK. Confirm that your residence and business structure are supported before applying.
Do I need to live in the UK to open a business account for a UK company?
Not in every case. Some providers accept applications from eligible overseas directors, while others require directors or relevant account users to be UK residents. Your company’s UK registration does not remove the provider’s personal residency and verification requirements.
What documents are needed for a non-resident business account?
Common requirements include a passport or other accepted identification, proof of residential address, company registration details, ownership information and evidence of business activity. The provider may request additional information about expected transactions, source of funds or the company’s operating address.
Is an international business account the same as a bank account?
Not necessarily. An international business account may be offered by a licensed bank or by an electronic money institution. The services and protection arrangements differ, so check the provider’s legal status and the specific terms of the account.
What is the difference between a business bank account and a multi-currency account?
A business bank account is used to manage company finances, while a multi-currency account provides features for holding or transacting in multiple currencies where supported. Some accounts offer both sets of functions, but the available currencies, transfer methods and fees vary.
Can I use more than one account for my UK company?
A company may use multiple accounts where the providers permit it. For example, one account may handle routine UK payments while another manages international transactions. Consider additional fees, accounting administration and the terms of each provider before opening multiple accounts.
How much does an international business account cost?
Costs vary by provider and may include setup charges, monthly fees, transfer charges, currency conversion costs and optional service fees. Compare the complete pricing structure against your expected transactions rather than relying on a headline monthly price.
Set Up Your UK Company With Form My Company
Choosing the right business account is an important part of preparing a UK company for trading internationally. The right option depends on where you live, how your company operates, the currencies you use and the financial services you require.
Form My Company helps international entrepreneurs with UK company formation and introductions to relevant banking options. Review your requirements, check provider eligibility and understand the fees before submitting an application.
Ready to establish your UK company? Visit Form My Company to explore the available company formation services and take the next step towards setting up your business.