Choosing the best online business bank account in the UK starts with comparing account fees, digital features, accounting integrations, payment options and eligibility requirements. Whether you are launching a limited company, managing a small business or moving your existing finances online, the right online business account can simplify daily transactions and help you maintain organised financial records.
Online business banking gives companies access to account management, transfers, card payments and transaction records through digital platforms. However, not every online business bank account offers the same services. Some providers operate as fully licensed banks, while others provide payment services through electronic money institutions or partner banks. Understanding these differences helps business owners select an account that suits their operations, financial requirements and plans for growth.
Form My Company supports entrepreneurs with UK company formation and related administrative requirements. This guide explains how to compare online business bank accounts, understand digital and fintech providers, review account costs and choose a suitable solution for your company.
What Is an Online Business Account?
An online business account is an account that businesses manage primarily through a website or mobile application. It allows business owners to monitor balances, make payments, receive money, review transactions and access statements without relying on regular branch visits.
An online business bank account may be available from a traditional bank with digital services or from a provider that operates mainly online. The exact features depend on the provider, account type and eligibility criteria.
For a newly incorporated UK company, a suitable business account can help separate company income and expenditure from personal finances. This supports clearer bookkeeping and makes it easier to prepare information for accountants, tax reporting and financial reviews.
Who Should Consider an Online Business Account?
Online business accounts can suit:
- Start-ups that want to manage their finances digitally.
- Sole traders who need a separate account for business transactions.
- Limited companies seeking organised company banking.
- Small businesses that want accounting software integrations.
- Consultants and service providers receiving payments electronically.
- E-commerce businesses managing sales through online platforms.
- Companies making regular domestic or international transfers.
The most suitable account depends on transaction volume, payment methods, cash requirements, business activity and the provider’s eligibility rules.
Best Online Business Bank Accounts in the UK: Comparison Table
The best account for one business may not suit another. Before applying, compare providers according to their account structure, costs, digital tools and available support.
| Provider | Account type to investigate | Potential advantages | What to check |
|---|---|---|---|
| Starling Bank | Digital business banking | App-based account management and business banking tools | Eligibility, account fees, transfer charges and available integrations |
| Tide | Digital business account services | Online application process and business administration features | Whether the selected product is a bank account or an e-money account, plus applicable fees |
| Monzo Business | Online business banking | Digital account management and transaction visibility | Eligibility, plan limits, payment costs and accounting integrations |
| Revolut Business | Digital business financial services | Multi-currency features and international payment options on eligible plans | Currency conversion costs, transfer limits and plan-specific charges |
| Barclays | Traditional bank with online business banking | Digital services supported by an established banking provider | Eligibility, account tariffs, application requirements and available support |
| NatWest | Traditional bank with digital business banking | Online account management and business banking services | Account charges, eligibility and the services included in each account |
This comparison is a starting point rather than a live ranking. Providers change their products, eligibility requirements and prices. Confirm the current terms directly with each provider before opening an account.
How to Choose the Best Online Business Banking Option
The best online business banking option is the one that supports your day-to-day transactions without unnecessary charges or administrative complications. Compare the following factors before making a decision:
- Monthly charges: Check whether the account has a monthly fee, an introductory offer or different pricing tiers.
- Transaction costs: Review charges for transfers, cash deposits, international payments and other services you expect to use.
- Accounting integrations: Check whether the account connects with software such as Xero or QuickBooks.
- Payment facilities: Consider debit cards, payment links, standing orders and direct debits where available.
- Access and permissions: Establish whether additional directors or employees can access the account and which permissions they receive.
- Customer support: Compare digital assistance, telephone support and branch access where relevant.
- Financial protection: Verify the provider’s regulatory status and whether the specific product qualifies for FSCS protection.
A business should compare the complete cost of operating an account rather than relying solely on an advertised free-account offer.
Online vs Digital vs Fintech Business Accounts
The terms online, digital and fintech business account are often used interchangeably, but they do not always describe the same type of service.
Online Business Bank Account
An online business bank account is managed through digital channels. It may be provided by a traditional high-street bank or a provider that operates without a branch network. Customers can usually access account information and complete supported transactions online.
Digital Business Bank Account
A digital business bank account places greater emphasis on app-based account management, digital onboarding and online financial tools. Features may include instant transaction notifications, spending categorisation, digital statements and accounting integrations.
The available features vary by provider and account plan, so check which functions are included before applying.
Fintech Business Account in the UK
A fintech business account UK search may return both licensed banks and financial technology providers offering payment accounts or other business financial services. Some providers use partner banks or electronic money arrangements rather than holding deposits as a bank themselves.
This distinction matters because regulatory arrangements and deposit protection may differ. Review the provider’s legal entity, account terms and protection arrangements before transferring company funds.
Online-Only Business Bank Account
An online-only business bank account is designed for customers who manage their banking digitally rather than visiting branches. It can suit companies that receive electronic payments and make most payments online.
However, an online-only account may not provide convenient cash deposits, in-person assistance or every specialist banking service. Businesses handling cash or requiring complex lending arrangements should check these limitations before choosing a provider.
Online Small Business Accounts: Features and Costs
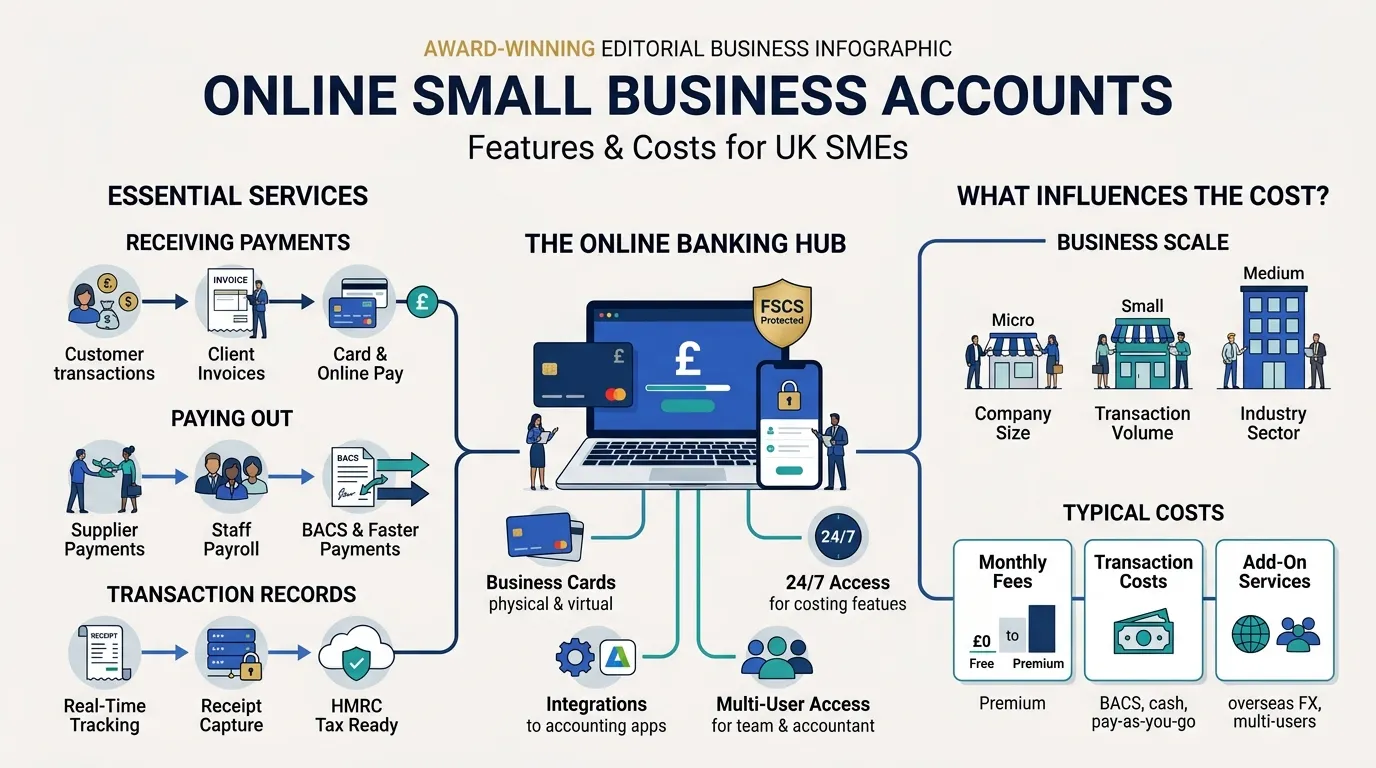
An online small business account should provide the essential services needed to receive payments, pay suppliers and maintain accurate transaction records. The right features depend on the company’s size, industry and financial activity.
What Should an Online Small Business Account Include?
Consider whether the account offers:
- A business debit card and secure digital access.
- Domestic transfers and supported payment methods.
- Downloadable statements and transaction records.
- Accounting software connections or data exports.
- Multiple users or permissions where required.
- Clear information about international transfers and currency conversion.
- Suitable customer support and account security controls.
Businesses with limited transaction volumes may prioritise low operating costs. Companies with employees, multiple directors or international customers may place greater importance on access controls, payment flexibility and reporting tools.
Online Business Account Pricing and What Is Included
Online business accounts may offer free basic plans, paid subscriptions or charges for individual services. A free account does not necessarily mean every transaction or feature is free.
When comparing prices, review the following:
| Cost or feature | What to check |
|---|---|
| Monthly account fee | Whether the account is free or subscription-based |
| Domestic transfers | Included transfer allowances and additional charges |
| International payments | Outgoing and incoming payment fees |
| Currency conversion | Exchange rates, mark-ups and conversion limits |
| Cash services | Deposit availability and applicable charges |
| Cards | Card issuance, replacement and additional card costs |
| Accounting tools | Included integrations and third-party subscription fees |
| Premium features | Which services require an upgrade |
Check the provider’s latest fee schedule and terms. Estimate the cost using your expected monthly transactions rather than selecting an account based on introductory pricing alone.
How to Open a Business Account Online
Many providers allow businesses to begin an application online. Approval is not automatic, and each provider sets its own identity checks, business eligibility rules and documentation requirements.
Step 1: Confirm Your Business Structure
Identify whether you operate as a sole trader, limited company or another eligible business type. A limited company is legally separate from its owners, so the account application generally needs to reflect the registered company details.
If your company is not yet incorporated, complete the relevant registration steps before applying where the provider requires an existing registered business.
Step 2: Compare Eligible Providers
Shortlist providers based on your business activity, expected transactions, payment requirements, software integrations and costs. Check whether the provider accepts your company type, industry and directors.
Step 3: Prepare the Required Documents
Depending on the provider and business structure, you may need:
- Company registration details and the company number.
- Details of directors and beneficial owners.
- Proof of identity for relevant individuals.
- Proof of address where required.
- Information about the company’s activities and expected transactions.
- Details of the registered office and trading address where requested.
- Supporting information about the source of funds or business relationships, if required.
Providers may request additional documents as part of their customer due diligence and Know Your Customer checks.
Step 4: Complete Identity and Business Verification
Submit the application through the provider’s official website or app. The provider may check the identities of directors and beneficial owners, verify company information and ask questions about expected account activity.
Application times vary. A digital application may be completed quickly, but additional verification or complex ownership structures can extend the process.
Step 5: Connect Your Financial Tools
Once the account is approved, set up available accounting integrations, transaction notifications, user permissions and payment controls. Review the account’s security settings and establish a routine for checking transactions and reconciling records.
Online Banks for Business vs High-Street Banks
Online banks for business can offer convenient digital account management, while traditional banks may provide branch access and a wider range of services for eligible customers. Neither option is automatically best for every company.
Advantages of Online Business Banks
Online business banks and digital providers may offer convenient account access, digital applications, transaction notifications and integrations with accounting platforms. These features can help business owners manage payments and records without relying on branch visits.
They can be particularly useful for companies that receive electronic payments, operate remotely or want to manage finances through a mobile application.
When a Traditional Bank May Be More Suitable
A traditional bank may be worth considering if your company regularly deposits cash, needs branch-based assistance or wants to explore a broader range of banking services. Availability depends on the provider, business profile and eligibility assessment.
Some traditional banks also offer online business accounts, so businesses do not necessarily have to choose between digital access and a high-street provider.
How to Make the Right Decision
Compare the actual account features rather than relying on labels such as digital bank, fintech or high-street bank. Focus on the services your business uses regularly, the total cost and any limitations that could affect future operations.
For guidance on matching banking services with your company’s bookkeeping setup, read our guide to business bank accounts that integrate with accounting software.
Digital Business Accounts for International Payments
A digital business account may support international payments, but available currencies, transfer routes, exchange rates and charges vary by provider.
Businesses trading internationally should check whether they can hold balances in different currencies, receive payments from overseas customers and pay suppliers in the countries where they operate. They should also compare the exchange rate used for currency conversion and any separate transfer fees.
A multi-currency feature can be useful when a business regularly receives or spends money in more than one currency. However, the number of supported currencies and the conditions for using them differ across providers.
Businesses with overseas customers or suppliers can also review our guide to UK business accounts for international payments to explore the considerations involved in choosing a suitable payment solution.
Choosing an Online Business Account for E-Commerce
An online business account can help e-commerce businesses manage sales receipts, supplier payments, platform expenses and refunds. However, the most suitable account depends on how the business receives payments and where its customers are located.
Online sellers should review payment settlement arrangements, transaction costs, accounting integrations and any restrictions affecting their business model. Companies selling internationally should also examine currency conversion charges and overseas transfer options.
For more specific guidance, read our article on business bank accounts for non-resident e-commerce founders. It covers considerations relevant to international founders operating online stores.
Online Business Accounts for Start-Ups
Start-ups should choose an account that meets their immediate requirements without creating unnecessary costs as the business grows. Early priorities may include receiving initial customer payments, paying suppliers, tracking expenses and maintaining clear records.
As the company expands, it may need additional cards, access for employees, higher transaction limits, international payments or more advanced accounting tools. Check whether the provider offers a suitable upgrade path and understand the charges before committing to a plan.
Newly formed companies can also read our guide to business bank accounts for non-resident startups for a comparison focused on the needs of international founders establishing a UK business.
How to Close a Dormant Business Bank Account
A dormant business bank account is an account that is no longer used for regular transactions. If the account is no longer required, closing it may help reduce administrative work and avoid applicable account charges.
Before requesting closure, check the provider’s process and confirm that no outstanding payments, direct debits, card transactions or pending transfers remain. Download statements and transaction records needed for bookkeeping and tax records. Update customers, suppliers and payment services with the replacement account details where necessary.
For a limited company, remember that closing a bank account does not close the company or remove its statutory filing and tax responsibilities. Keep the relevant company records and confirm that outstanding financial obligations have been addressed before completing the closure.
Common Mistakes When Choosing an Online Business Account
Choosing an Account Based Only on Price
A free account may have limits or charges for services your company uses regularly. Compare the full tariff, including transfers, cash services, cards and currency conversion.
Ignoring Business Eligibility
Providers may restrict particular industries, company structures, countries or ownership arrangements. Confirm eligibility before relying on an account for your business launch.
Overlooking Accounting Compatibility
An account without a suitable integration may require more manual bookkeeping. Check whether the provider connects with your accounting software or allows transactions to be exported in a format your accountant can use.
Failing to Check Protection Arrangements
Do not assume that every digital or fintech account has the same deposit protection. Check whether the provider is a bank, whether the specific account qualifies for FSCS protection and which legal entity holds the funds.
Not Planning for Business Growth
An account that works for a small number of monthly transactions may become less suitable as payment volumes increase. Review transaction limits, user permissions, international services and upgrade costs before choosing a provider.
How Form My Company Supports Your Business Setup
Selecting an online business account is one part of establishing a UK company. Business owners also need to consider incorporation details, director information, registered office requirements and ongoing administrative responsibilities.
Form My Company provides online company formation services and support with the information required to establish a UK business. Preparing accurate company details can help you approach banking applications with a clearer understanding of your business structure and registration information.
Before applying for an account, confirm the provider’s eligibility criteria and prepare the documents it requests. Account approval remains the decision of the bank or financial services provider.
Frequently Asked Questions
What Is the Best Online Business Bank Account in the UK?
The best account depends on your business structure, transaction volume, costs, accounting requirements and payment needs. Compare digital providers and traditional banks, review their current terms and confirm eligibility before applying.
Can I Open a Business Bank Account Online?
Many UK providers accept applications online. You may need company registration details, proof of identity, address information and details about directors or beneficial owners. The provider will assess your application before deciding whether to open the account.
Are Online Business Accounts Different from Digital Business Accounts?
The terms overlap. An online business account is managed digitally, while digital business account commonly describes a service designed around app-based or online account management. The provider’s regulatory status and actual features are more important than the label.
Are Fintech Business Accounts Protected by the FSCS?
Protection depends on the provider, the account structure and the legal entity holding the money. Some accounts offered by fintech companies are eligible for FSCS protection through a licensed bank, while others may use different safeguarding arrangements. Check the provider’s official terms and the applicable protection rules before depositing funds.
Can I Close a Dormant Business Bank Account?
Yes, subject to the provider’s closure process and any outstanding transactions or obligations. Download the statements you need, cancel or transfer payment arrangements and update relevant parties before closing the account. Closing the account does not close a limited company.
What Is the Difference Between an Online Business Account and a Personal Account?
A business account is designed for business transactions and may provide business-specific features, records and permissions. A limited company should maintain clear separation between company finances and personal money. Check the provider’s terms and your business structure when selecting an account.
Can an Online Business Account Support International Payments?
Some accounts support international transfers and multiple currencies, while others focus mainly on domestic payments. Compare supported currencies, exchange rates, transfer charges and country restrictions before choosing an account for international trading.
Set Up Your UK Company with Confidence
Choosing the right online business account can help you manage payments, organise financial records and support your company’s day-to-day operations. Compare account features, fees, eligibility and protection arrangements before making your decision.
If you are preparing to establish a UK business, Form My Company can support you with online company formation and related administrative requirements. Visit Form My Company to explore the available services and take the next step towards setting up your company.