Choosing the best business account for international payments can help UK companies reduce foreign exchange costs, manage multiple currencies and make cross-border transactions more efficiently. The right business bank account for international payments should match how your company receives overseas revenue, pays international suppliers and manages foreign-currency balances.
At Form My Company, we help entrepreneurs establish UK limited companies and connect with banking options suited to their business requirements. This guide compares key account providers, explains multi-currency features, outlines international transfer fees and highlights what import-export businesses should consider before applying.
Account eligibility, fees, available currencies and protection arrangements vary between providers. Always check the latest terms directly with the provider before opening an account.
What Is a Business Account for International Payments?
A business account for international payments is designed to help companies send and receive money across national borders. Depending on the provider, it may support foreign-currency balances, international transfers, local receiving details and payments to overseas suppliers or customers.
A standard UK business current account may be sufficient for a company that only trades in pounds sterling. However, businesses operating across several markets often need additional currency and payment features.
An international business account can be useful for:
- E-commerce businesses receiving marketplace payments in different currencies.
- Importers paying manufacturers and suppliers overseas.
- Exporters collecting payments from international customers.
- Consultants and service providers invoicing clients abroad.
- Companies paying overseas contractors, software providers and employees.
- UK businesses managed by directors who live outside the United Kingdom.
The best option depends on transaction volume, currencies, transfer destinations, account eligibility and the amount of money the company expects to hold.
Best Business Accounts for International Payments Compared
There is no single best business bank account for international payments for every company. Some providers specialise in currency conversion and cross-border transfers, while others offer broader business banking facilities and deposit protection through a licensed banking partner.
The following comparison outlines the general positioning of several commonly considered providers. Availability, fees and eligibility should be verified before applying.
| Provider | Main strengths | Important considerations |
|---|---|---|
| Wise Business | International transfers, multi-currency balances and foreign-currency receiving features | Check conversion charges, transfer fees, currency availability and safeguarding arrangements |
| Airwallex | Multi-currency business operations, global payments and business expense tools | Eligibility and available features depend on business location and account approval |
| Revolut Business | Business payment tools, currency features, cards and options for growing teams | Plans, transaction allowances, exchange fees and eligibility vary |
| Tide | UK business account services and business administration features | Confirm international payment availability, charges and the applicable banking arrangements |
| Starling Bank | UK digital banking and international payment services | Check residency, address and business eligibility requirements before applying |
This comparison is a starting point rather than a ranking. A provider with attractive foreign exchange pricing may not be suitable if it does not support your business structure, residence or payment destinations.
Wise Business for International Transfers
Wise Business is worth considering for companies that regularly receive and send money in different currencies. Its features can include multi-currency balances, international transfers and local receiving details for supported currencies.
Before choosing an account, review the fee for each currency conversion, the cost of receiving payments and the availability of the currencies your business uses. Also distinguish between safeguarding arrangements and FSCS deposit protection, as these are not the same.
Airwallex for Global Business Operations
Airwallex offers services designed for businesses with international payment requirements. Depending on eligibility and the selected service, businesses may access multi-currency facilities, international transfers, business cards and expense management tools.
It may suit companies working with overseas suppliers, international customers or teams operating across multiple markets. Confirm the supported jurisdictions, onboarding requirements and applicable fees before applying.
Revolut Business for Growing Companies
Revolut Business combines business payment features with tools that can support companies trading internationally. Available services and pricing depend on the plan, business location and eligibility.
Compare the account’s included transfer allowances, exchange arrangements, currency support and any charges that apply when you exceed plan limits. Companies with frequent or high-value transfers should calculate the total expected cost rather than comparing monthly fees alone.
Tide for UK-Focused Businesses
Tide provides business account services and administration tools for UK businesses. It may be worth comparing if your company primarily operates in the UK but also makes occasional international payments.
Check the current international transfer options, applicable charges and which regulated institution provides the relevant account services. Do not assume that every feature available through a provider is included in every account.
Starling Bank for UK Business Banking
Starling Bank is a UK-licensed digital bank offering business banking services and international payment facilities, subject to its terms and eligibility requirements.
It may appeal to businesses seeking a broader UK banking relationship alongside international payment functionality. Overseas directors should verify the current residency, address and company requirements before beginning an application.
Online Business Accounts vs Traditional UK Banks
Online business accounts and traditional high-street banks can both support international transactions, but their pricing structures, onboarding processes and available features differ.
Online and Digital Business Accounts
Specialist digital providers often focus on international transfers, foreign-currency conversion and multi-currency account features. Their online platforms can make it easier to review transactions, manage balances and initiate payments remotely.
Potential advantages include:
- Access to several supported currencies through one platform.
- Transparent transfer and conversion fees, depending on the provider.
- Digital onboarding and online account management.
- Payment tools for companies trading across multiple markets.
- Integrations with selected accounting and business software.
However, digital access does not mean every non-resident founder or overseas company will qualify. Providers conduct identity, company and business-activity checks, and their services may be restricted by jurisdiction.
If your company is managed from overseas, review our guide to UK business bank accounts for non-residents for more information about residency requirements and account selection.
Traditional High-Street Banks
Traditional banks may suit companies that need a wider banking relationship, access to lending or other financial services. They can also support international payments, although the cost and process depend on the account and payment method.
Before choosing a traditional bank, ask about international transfer charges, exchange-rate margins, intermediary bank fees, payment limits and onboarding requirements. Businesses with overseas directors should confirm whether the bank accepts their residency and company structure.
The right choice is the account that supports your actual transactions at an acceptable total cost, rather than the provider with the most familiar name.
Multi-Currency Business Bank Accounts and Foreign-Currency Balances
A multi-currency business bank account allows a company to hold, receive or send money in more than one currency, subject to the provider’s available services. It can help businesses reduce unnecessary conversions and manage international cash flow.
For example, a UK company receiving payments in euros may be able to retain those funds in euros and use them to pay a supplier who also invoices in euros. This can avoid converting the same money into pounds and then back into euros, although account, transfer or withdrawal fees may still apply.
When Is a Multi-Currency Business Account Useful?
A multi-currency account may be useful when your company:
- Receives recurring payments in currencies other than GBP.
- Pays overseas suppliers in their invoicing currency.
- Maintains customers or operations in multiple countries.
- Needs to manage foreign-currency revenue and expenses.
- Wants greater visibility over currency balances and conversion costs.
The best multi-currency business account is not necessarily the one supporting the largest number of currencies. Prioritise the currencies, countries and payment methods your business actually needs.
Foreign-Currency Accounts vs Multi-Currency Accounts
A foreign-currency business account may be designed around a particular currency, whereas a multi-currency account may let a company manage several currencies through one platform.
Before applying, establish whether the account supports holding balances, receiving local payments, sending international transfers and converting funds. These capabilities are separate, and a provider may support one without offering all the others.
Also check whether the receiving details are local to the relevant market, whether incoming payments carry a fee and whether funds are automatically converted when received.
Receiving International Payments From Overseas Customers
Receiving international payments involves more than selecting an account that accepts foreign transfers. The payment method, sending country, receiving currency and intermediary banks can all affect the amount received and the time taken.
When comparing the best business bank account for receiving international payments, review the following:
- Receiving currencies: Confirm that the provider supports the currencies your customers use.
- Local account details: Check whether the provider supplies local receiving details for the relevant currency and country.
- Incoming payment fees: Review charges for domestic-style transfers and international wires.
- Currency conversion: Establish whether incoming payments are converted automatically or can remain in their original currency.
- Transfer speed: Check typical processing times and the effect of weekends, holidays and intermediary banks.
- Payment references: Confirm that the account supports the references and reconciliation processes your finance team requires.
International wire transfers may use the SWIFT network, depending on the payment route and provider. SWIFT-related payments can involve intermediary institutions and additional charges, so the advertised transfer fee may not always represent the total cost.
Businesses receiving payments through marketplaces or payment processors should also check settlement currencies, withdrawal fees and supported account details.
For businesses with significant online sales, our guide to business bank accounts for non-resident e-commerce founders covers banking considerations specific to online selling.
International Payment Fees and Exchange Rates
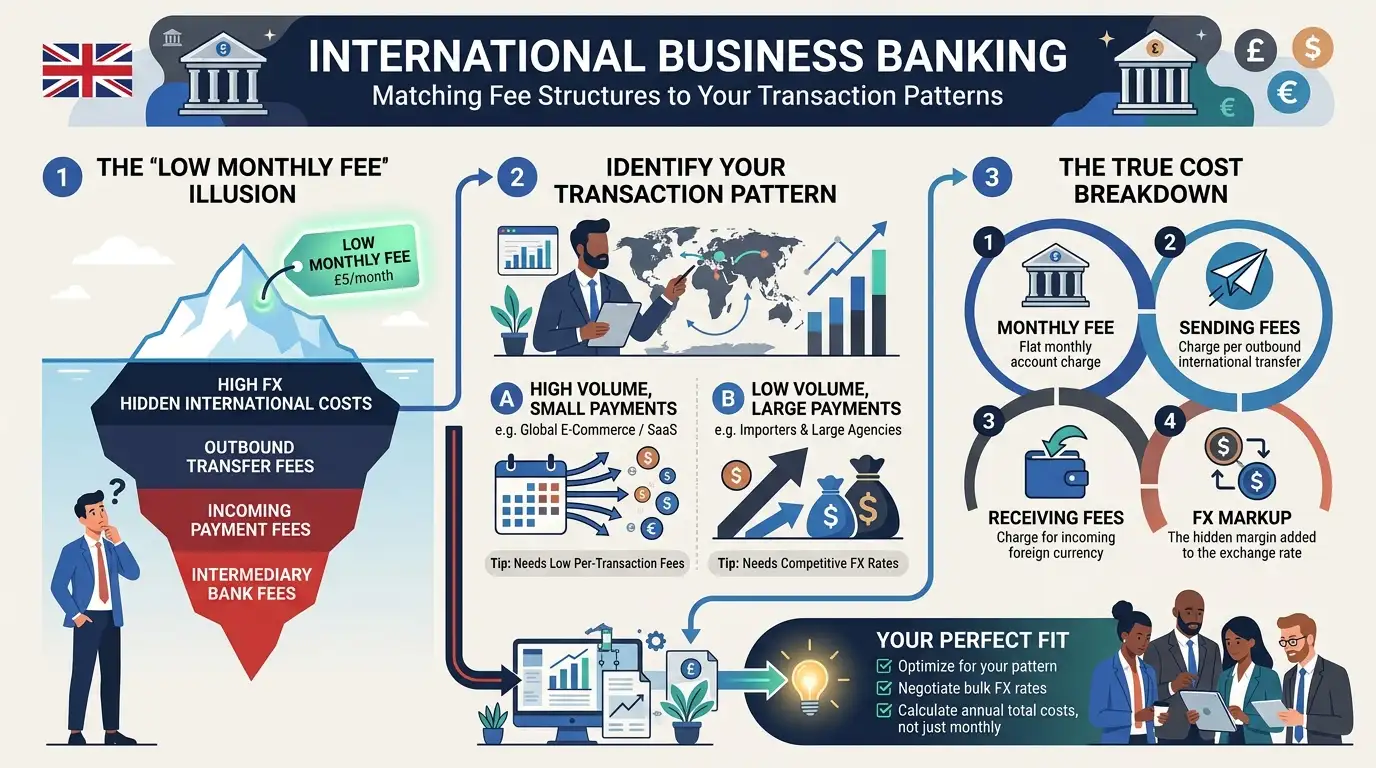
The best business bank account for international payments should offer a fee structure that works for your transaction pattern. A low monthly account fee does not automatically mean low international payment costs.
Foreign Exchange Fees
Foreign exchange, or FX, costs arise when money is converted from one currency into another. Providers may charge a stated conversion fee, include a margin in the exchange rate or apply a combination of charges.
Compare the rate offered with an appropriate market reference and check the total amount the recipient will receive. A transfer advertised as having no separate fee can still be expensive if the exchange rate includes a substantial margin.
International Transfer Fees
Providers may charge for outgoing payments, incoming transfers or specific payment methods. International wire transfers may also incur intermediary or recipient-bank fees.
Ask whether the quoted charge covers the complete transfer route and whether the recipient receives the full intended amount. The answer can differ by destination, currency and payment network.
Monthly Plans and Transaction Allowances
Some providers offer different pricing plans with varying transaction allowances or service features. Review the charges that apply when you exceed an allowance, use particular currencies or make payments outside supported regions.
Estimate your likely monthly transfer volume, average payment size and currency conversions before comparing accounts. This gives you a more realistic view of the cost.
Example of Comparing Total Costs
Suppose a company receives revenue in euros and pays suppliers in US dollars. It should compare the cost of receiving euros, holding the balance, converting euros to dollars and sending the outgoing payment.
The relevant comparison is the total cost of completing the company’s payment cycle, not simply the cost of one transfer. Actual costs will depend on the provider’s current pricing and the currencies involved.
Best Business Bank Account for Import-Export Businesses
Import-export companies often make frequent payments to overseas suppliers while receiving revenue from customers in different markets. A suitable business currency account can help them manage those flows and maintain clearer records of foreign-currency transactions.
When comparing accounts for import-export activity, consider:
- Whether the provider supports your supplier and customer currencies.
- The cost of sending high-value or recurring payments.
- The availability of local receiving details.
- Transfer limits and any additional verification requirements.
- Access to transaction reports and accounting integrations.
- The ability to retain foreign-currency balances.
- How the account handles refunds, returned payments and payment investigations.
Companies paying manufacturers or distributors should also consider payment timing and working-capital requirements. A delayed international transfer can affect supplier relationships and delivery schedules even when the fee is competitive.
Businesses with complex trade flows should confirm whether the provider supports their payment destinations, transaction sizes and business activities before opening an account.
Eligibility and Documents Required to Open an Account
Account requirements vary by provider. A UK-registered company does not automatically qualify for every business account, and acceptance depends on the provider’s onboarding checks and commercial policies.
Applicants commonly need some or all of the following:
- Certificate of Incorporation and company registration number.
- Details of directors, shareholders and beneficial owners.
- Valid identity documents, such as a passport.
- Proof of residential address for relevant individuals.
- UK registered office details and other company information.
- A description of the company’s activities and expected transactions.
- Website, contracts, invoices or other evidence supporting the business model, where requested.
- Information about source of funds and expected payment destinations, where required.
Providers may conduct Know Your Customer checks, commonly called KYC, and additional business verification. They may request further documents if the ownership structure, country of residence or planned transactions require clarification.
Can Overseas Directors Apply?
Some providers accept applications from companies with overseas directors, while others apply residency or address restrictions. Eligibility can depend on the director’s country of residence, the company’s registration details and the nature of the business.
If you are a non-resident founder, check the provider’s requirements before preparing an application. A registered office address is a company administration requirement and does not, by itself, guarantee that a bank will approve an account.
How Form My Company Can Help
Form My Company helps entrepreneurs establish UK limited companies and provides company formation support, including the relevant registration details and registered office services where included in the selected package.
We can also help founders explore banking options that align with their company and international payment requirements. Account approval, final eligibility and the provider’s document requirements remain the provider’s responsibility.
Choosing the Right International Business Account
The best international business account is the one that supports your company’s payment requirements, operating countries and financial processes.
Businesses that want to simplify bookkeeping should also compare business bank accounts that integrate with accounting software to understand how banking integrations can streamline financial administration.
Before making a decision, work through these checks:
- List your currencies: Identify the currencies you receive, hold and send.
- Map your payment destinations: Check whether the provider supports the countries and payment methods you need.
- Calculate total fees: Include account charges, FX costs, receiving fees and transfer fees.
- Review eligibility: Confirm company, director, residency and address requirements.
- Check protection arrangements: Understand whether funds are held with a licensed bank or safeguarded by an e-money institution, and what protections apply.
- Assess administration features: Review statements, user permissions, cards and accounting integrations.
- Plan for growth: Make sure the account can support your expected payment volume and operational needs.
Newly formed companies may have different requirements from established international traders. If you are setting up a new venture, read our guide to business bank accounts for non-resident startups for additional considerations.
FSCS Protection and Safeguarding: What Businesses Should Know
FSCS deposit protection and e-money safeguarding are different arrangements. Eligible deposits held with authorised banks may qualify for Financial Services Compensation Scheme protection, subject to the applicable rules and limits. E-money institutions generally safeguard customer funds under the relevant regulatory framework, but safeguarded funds are not the same as FSCS-protected bank deposits.
Do not assume that every fintech brand provides the same protection. Check which legal entity provides the account, where the funds are held and which protections apply to your particular product.
Businesses holding significant cash balances should consider their protection requirements alongside international payment costs and operational convenience.
Frequently Asked Questions
What Is the Best Business Account for International Payments?
The best option depends on the currencies your company uses, transfer destinations, transaction volume, fees and eligibility. Wise Business and Airwallex are worth comparing for multi-currency requirements, while Revolut Business, Tide and Starling may suit different combinations of international and UK banking needs. Check current terms before applying.
What Is the Best Business Bank Account for Receiving International Payments?
Look for an account that supports your incoming currencies, offers suitable receiving details and clearly explains incoming transfer and conversion fees. Also check whether payments use local transfer networks or SWIFT and whether intermediary charges may apply.
What Is the Best Multi-Currency Business Bank Account?
There is no universal winner. Compare supported currencies, holding features, receiving details, conversion rates, transfer costs and eligibility. Choose an account based on your actual transactions rather than the number of currencies advertised.
Can a UK Company Open an International Business Account Online?
Some providers allow eligible businesses to apply online. However, the process may include identity verification, company checks and requests for additional documents. Online applications do not guarantee approval, particularly where directors or beneficial owners live overseas.
Can Non-Residents Open a UK Business Account for International Payments?
Some providers accept UK companies with non-resident directors, but policies vary. Residency, proof of address, ownership structure, business activity and the applicant’s country can affect eligibility. Confirm the requirements directly with each provider before applying.
What Is the Difference Between a Foreign-Currency Account and a Multi-Currency Account?
A foreign-currency account may focus on one currency, while a multi-currency account can support several currencies. The exact features vary, so check whether you can hold, receive, convert and send each currency you need.
How Much Do International Business Payments Cost?
Costs depend on the provider, payment destination, currency, amount and transfer method. Charges may include a transfer fee, FX fee, exchange-rate margin and intermediary bank fees. Compare the total cost and the amount the recipient will receive.
Do Import-Export Businesses Need a Multi-Currency Account?
Not every import-export business needs one, but it can be useful when a company regularly receives and pays money in different currencies. Holding funds in the relevant currency may reduce unnecessary conversions, depending on the payment arrangements and fees.
Is Money in a Fintech Business Account Protected by the FSCS?
Not necessarily. Protection depends on the legal entity and the type of account. Eligible bank deposits may qualify for FSCS protection, whereas e-money safeguarding is a different arrangement. Check the provider’s current terms and the applicable protections before depositing funds.
Set Up Your UK Business for International Payments
Choosing the right business account for international payments can help your company manage currency conversion, overseas suppliers and cross-border customer revenue more effectively. Compare providers according to the currencies you use, your expected payment volume, account eligibility and the total cost of transactions.
Form My Company helps entrepreneurs establish UK limited companies and explore banking options suited to their business needs. Start your UK company formation today and review the current eligibility and account terms of your preferred provider before applying.